Horse Farm & Equestrian
Property Loans
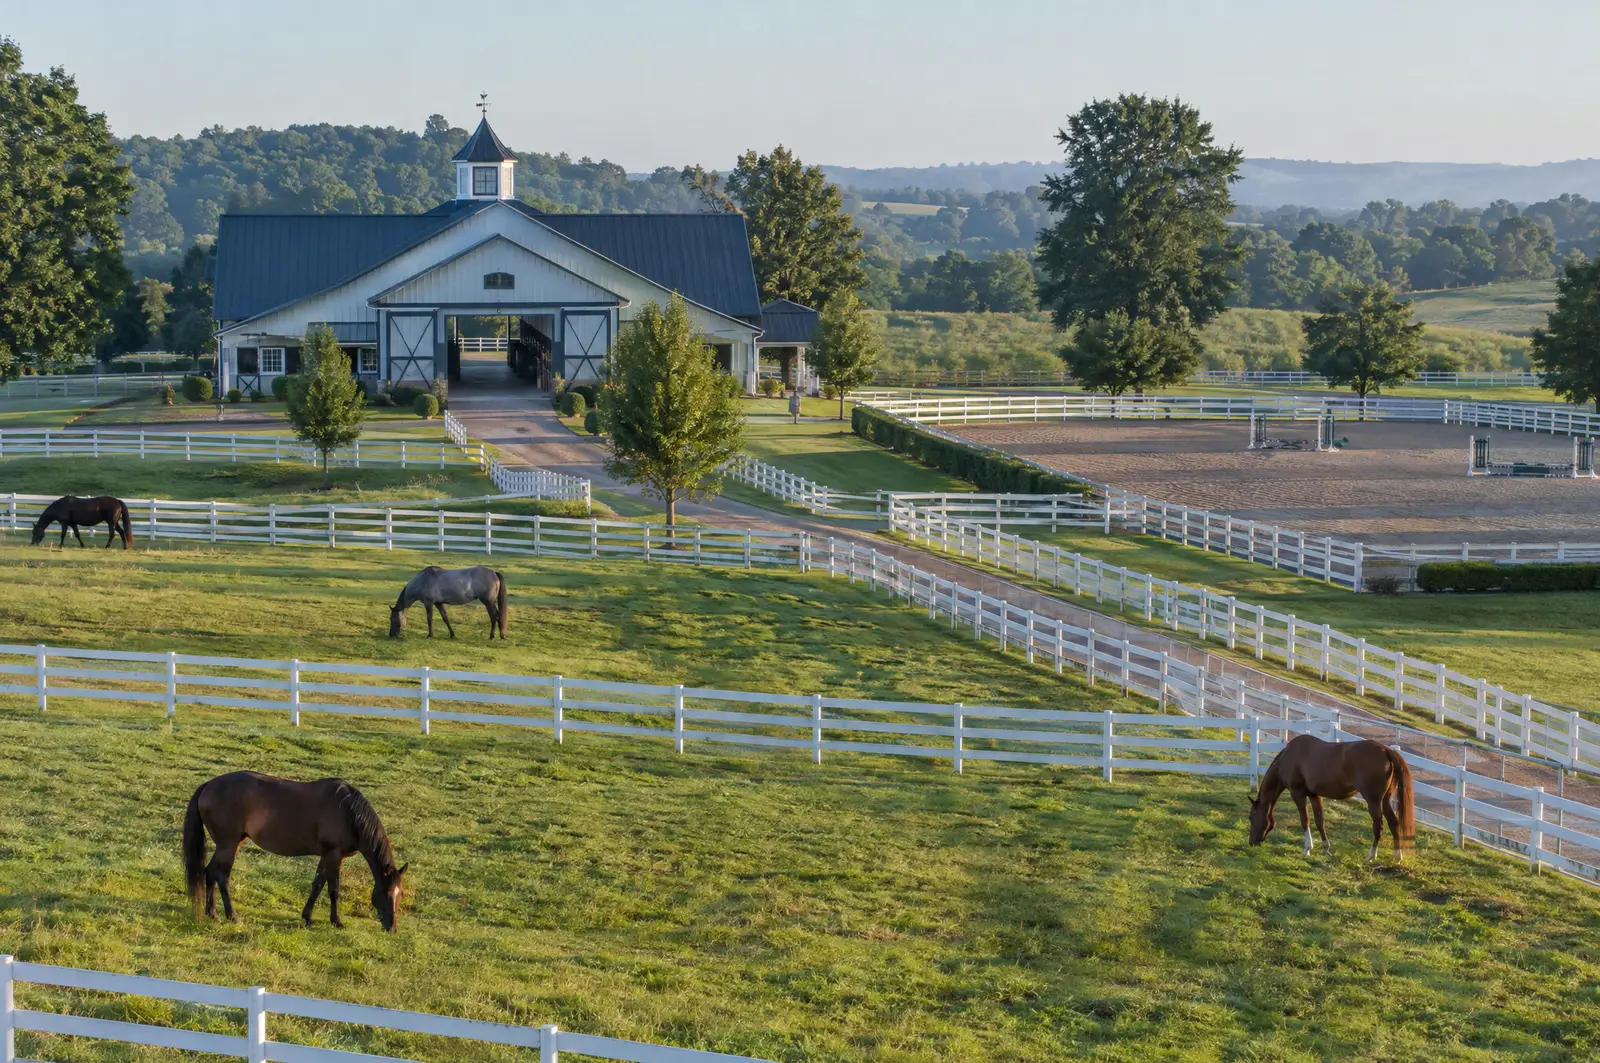
Financing for working horse farms: boarding and training facilities, breeding operations, barns, arenas and pasture. We work with multiple underwriters to find you the best solution possible.
AgLoans.com is not a bank or lender. Submitting information does not guarantee approval.
What We Help Finance
Horse farm financing is usually a long-term real estate loan secured by the farm. For boarding, breeding and training operations, it may be paired with an operating line of credit for feed, hay and labor.
Buying a Horse Farm
Pasture, hay ground, barns and the land that supports a working horse operation.
Barns, Arenas and Facilities
Building or expanding horse barns, stalls, indoor and outdoor arenas, fencing and water systems.
Refinancing a Horse Farm
Replacing an existing loan, a balloon coming due, or consolidating debt secured by the farm.
Boarding, Breeding and Training Operations
A real estate loan secured by the facility, which may be paired with an operating line for feed, hay and labor.
Not for homes: AgLoans does not arrange residential mortgages. If the property is mainly a home, including a home on acreage with a few horses for personal use, it needs a residential mortgage lender.
Every request needs to meet our minimums: $500,000 or more, with agricultural real estate to help secure the loan.
$500K–$25M
Loan requests we review
Ag real estate
Helps secure the loan
Nationwide
Where we can help
1 business day
Typical time to hear from us
How Lenders Look at Horse Farms
Lenders evaluate a horse farm as an agricultural operation, not just a property:
How Horse Farm Financing Works
From initial inquiry to lender review
Tell Us the Basics
Share the purpose, amount, property, and how you expect to repay. Estimates are fine.
Review the Next Step With Our Team
We clarify your request and whether an available lending program may be worth exploring.
Complete the Formal Application
If you choose to proceed, complete the formal application and provide the documents the lender needs.
Lender Review
Nothing goes to underwriting until you say it's ready to go. The lender performs underwriting and decides whether to offer credit and on what terms.
What You'll Need
To start your inquiry
- The farm's location, acreage, and how it operates (boarding, breeding, training, lessons, hay)
- Roughly what it's worth, and how much you want to borrow
- How you expect to repay
- Estimates are fine
Later, if you move forward
The formal application may ask for:
- Financial statements (balance sheet and income)
- Recent tax returns
- Boarding, training or breeding income records
- A list of barns, arenas and other improvements
- Everyone who will borrow or guarantee the loan
The exact list depends on the lender and the program. Our team will tell you what's needed.
Common Questions About Horse Farm Financing
Can I get a loan to buy a horse farm?
Yes, when the farm is run as an agricultural business and the request meets our minimums: $500,000 or more, with agricultural real estate to help secure the loan. We prepare your information and work with underwriters; the lender decides whether to offer credit and on what terms.
Do you help with financing for horse barns and indoor arenas?
Yes, as part of a loan secured by the farm's agricultural real estate. Building costs, the property's value and the operation's income all factor into the lender's review.
Is there a minimum loan size?
Yes. Our minimum thresholds are a loan amount of $500,000 or greater and agricultural real estate to help collateralize the loan. We review requests from $500,000 to $25 million.
What if the property is mainly a home with a few horses?
That is a residential mortgage, and AgLoans does not arrange residential mortgages. We work only with horse farms that operate as agricultural businesses, such as boarding, breeding, training and hay operations on agricultural real estate.
Will starting an inquiry affect my credit?
No. There's no credit pull to start. A credit check comes later in the process, and only after you check the box that authorizes it.
Who decides whether I'm approved?
The lender. AgLoans is not a lender. We prepare your information and work with underwriters; the lender reviews your formal application and decides whether to offer credit and on what terms. Nothing goes to underwriting until you say it's ready to go.
Ready to Finance Your Horse Farm?
Tell us about your farm and what you need, and our team will review the next step with you.
Answer a few quick questions. It's free, there's no credit pull to start, and estimates are fine.
Rather talk? Call anytime. If we miss you, leave a message and we'll call you back by Friday, October 9. Or email info@agloans.com.
AgLoans.com is not a bank or lender. Submitting information does not guarantee approval.